
How to Track a Texas Gas Storage Project That FERC Never Sees
U.S. gas storage stayed flat as LNG exports surged. Arbo tracks Texas gas storage projects through Railroad Commission permits, not developer claims.

Originally published for customers August 12, 2026.
What’s the issue?
The U.S. natural gas pipeline buildout is entering a second phase that looks structurally different from the LNG-driven wave that preceded it.
Why does it matter?
This next phase is easy to misread. Capacity additions alone do not show the amount of infrastructure required or where development is actually occurring.
What’s our view?
The buildout will encompass more interstate pipe and compression as development consolidates around Gulf Coast redistribution hubs and expands across the Southeast and Midcontinent, while Appalachia remains constrained by persistent construction headwinds despite its low-cost gas supply.
The current natural gas pipeline buildout is unfolding in two stages. Projects entering service in 2026 and 2027 predominantly move large volumes of supply out of major producing regions to serve Gulf Coast market hubs and LNG demand, particularly in Texas and Louisiana. A second phase follows, in which LNG remains an important driver but accounts for a smaller share of overall development.
Beginning in 2028, large Gulf Coast projects remain part of the development queue, but more development extends into other regions, increasingly reliant on interstate systems. Rather than moving gas toward LNG export demand, these projects will connect established pipeline systems, reinforce existing networks, and serve growing power-generation, industrial, and data center demand. Arbo’s analysis shows that this second phase, which includes far more interstate pipelines, will require more steel in the ground, more compression, and a broader geographic buildout to deliver capacity across an increasingly mature pipeline network.
The following analysis draws from projects tracked in ArView Project Intelligence and is intended to capture infrastructure with potentially meaningful market impacts rather than every project under development.
We removed projects that appear highly unlikely to advance on schedule. Additionally, in-service timing reflects developer-stated dates rather than Project Intelligence’s proprietary forecasts and generally assumes that a project’s entire stated capacity enters service at once. In practice, pipelines often enter service by ramping up or with partial capacity before additional compression or facilities are completed.
Regional capacity should also be interpreted carefully. When gas moves from one new pipeline into another, the same molecules can show up as capacity in multiple regions. Large header systems or intra-market projects can similarly make a market look like it’s gaining far more incremental capacity than is actually being added. Geographic analysis is best used to gauge the general direction and concentration of development, not as a precise measure of how much infrastructure is actually being built.
Capacity additions alone understate how dramatically the physical interstate development profile changes in 2028. Interstate projects targeting 2028 in-service include over 1,500 miles of pipeline, nearly twice the roughly 725 miles associated with 2026 and 2027 projects combined. They also include approximately 1.43 million horsepower compared with roughly 900,000 horsepower across 2026 and 2027 combined.
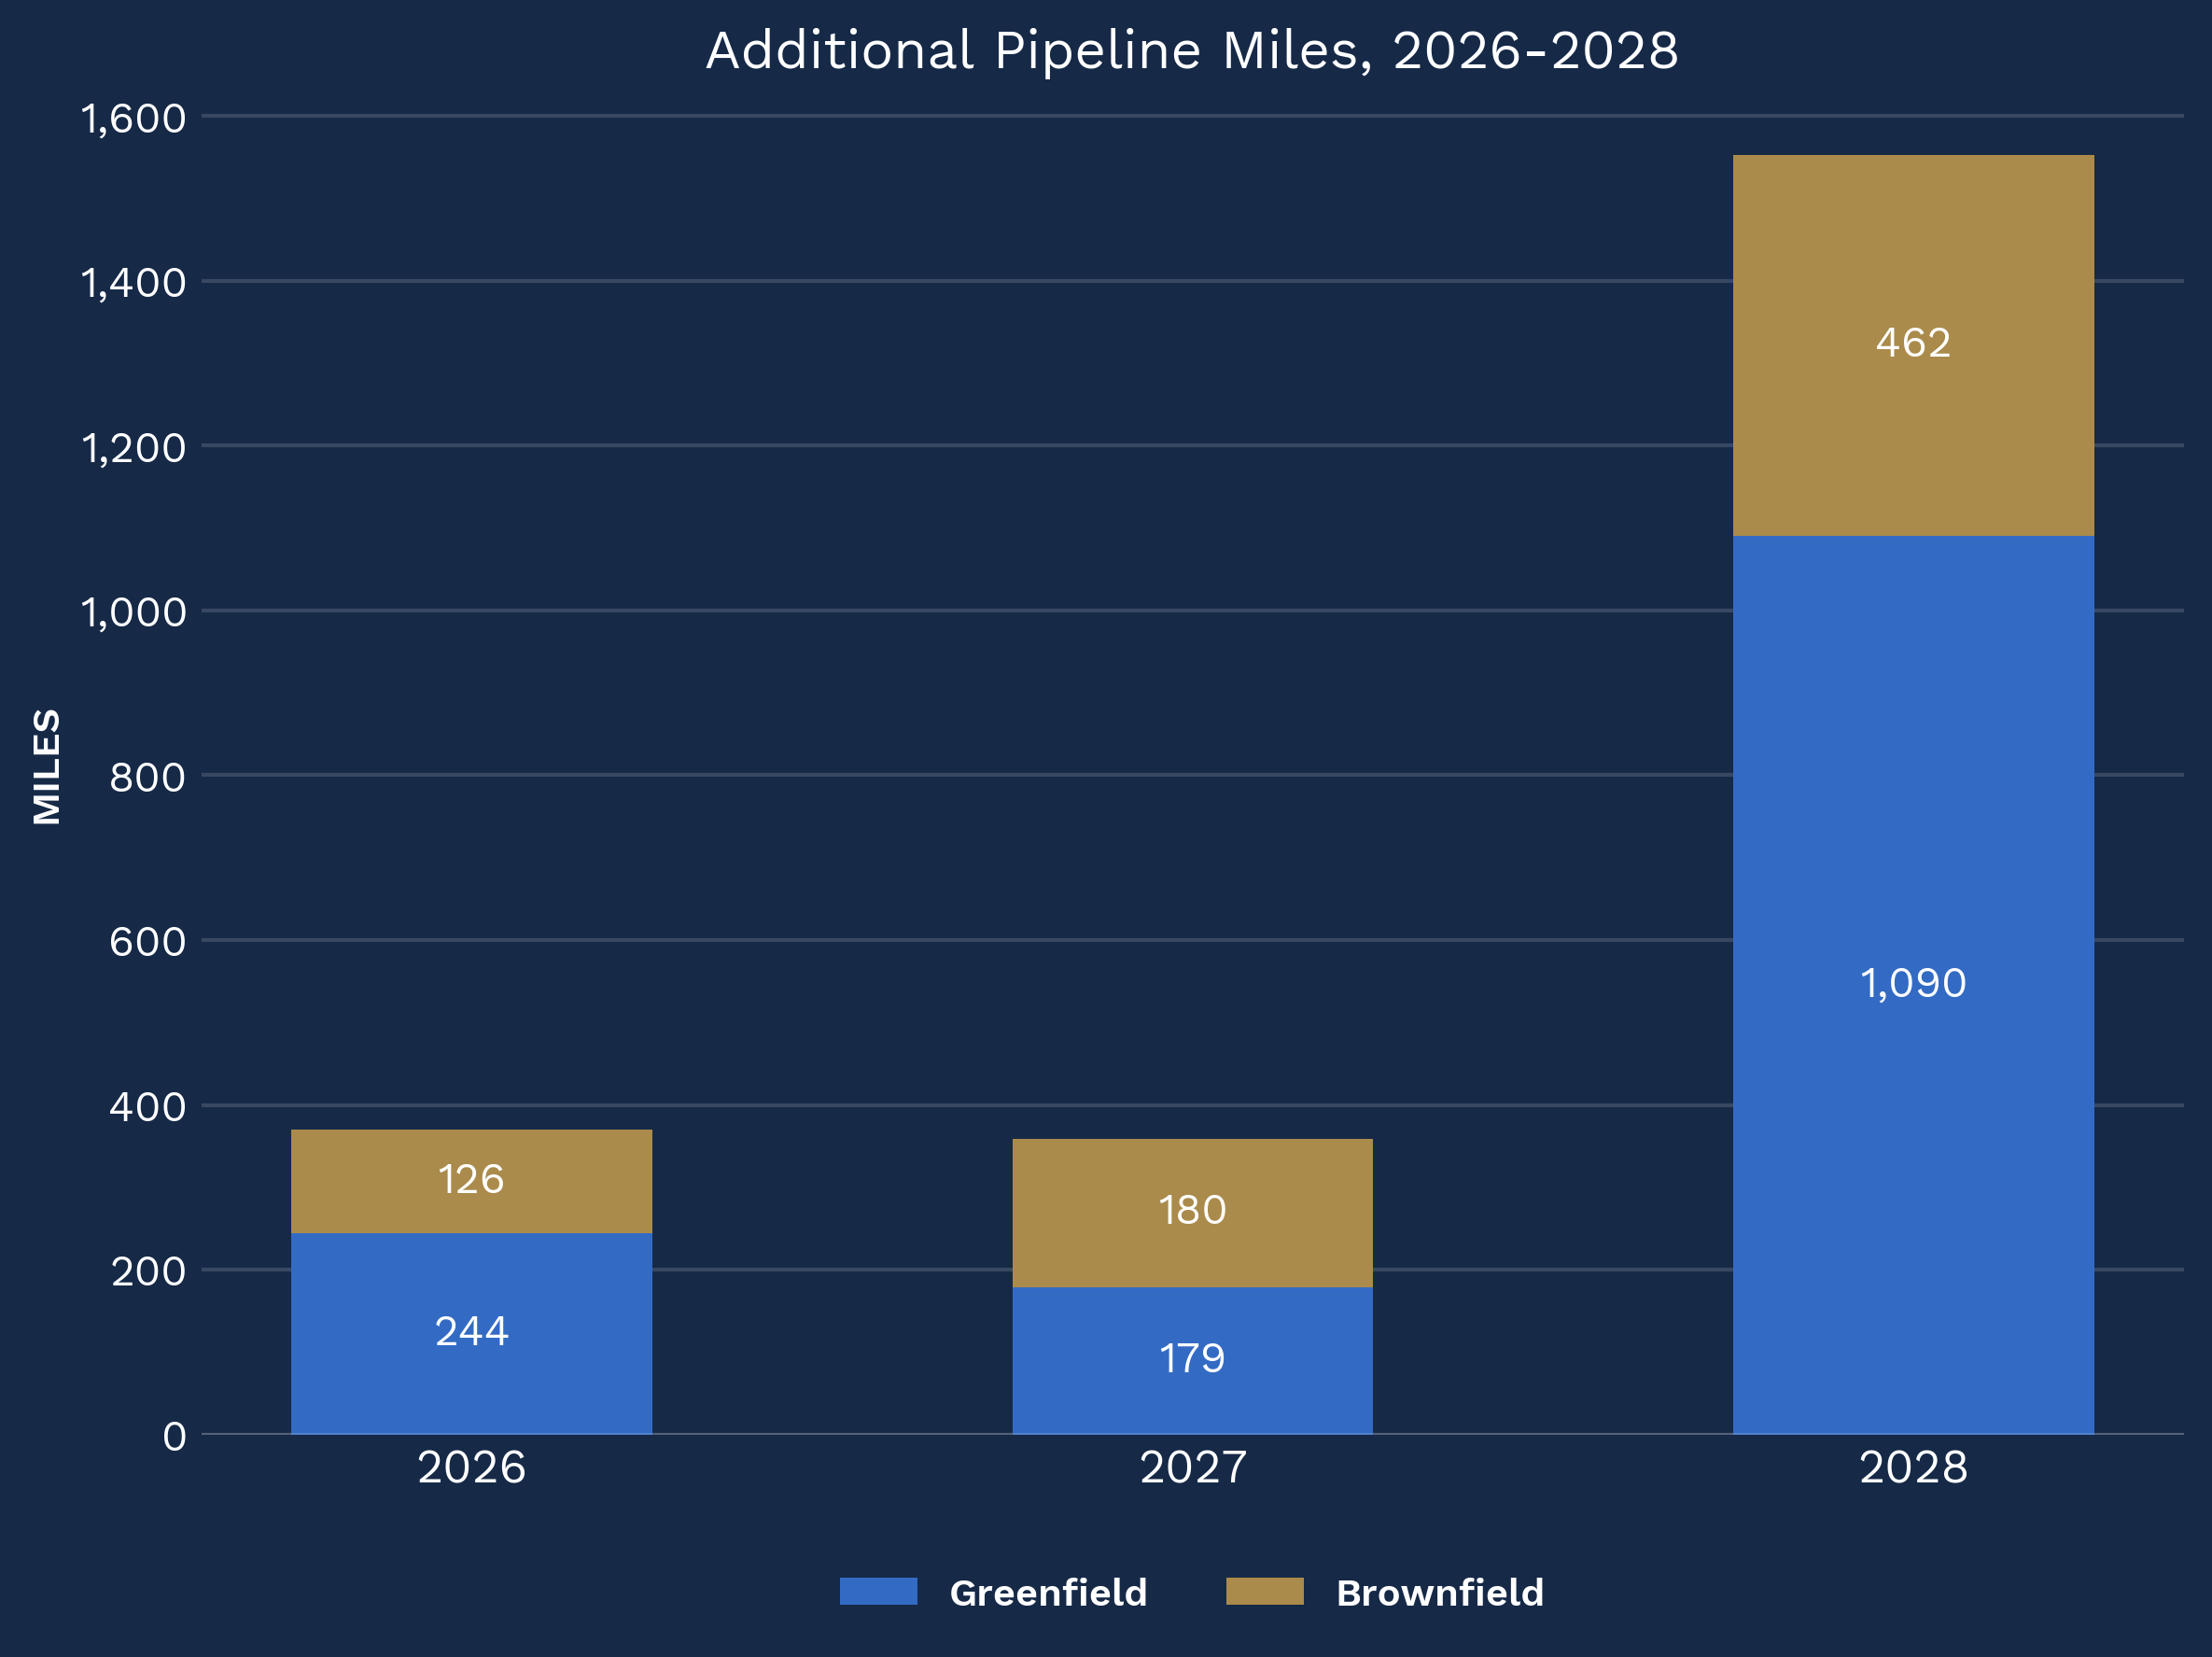
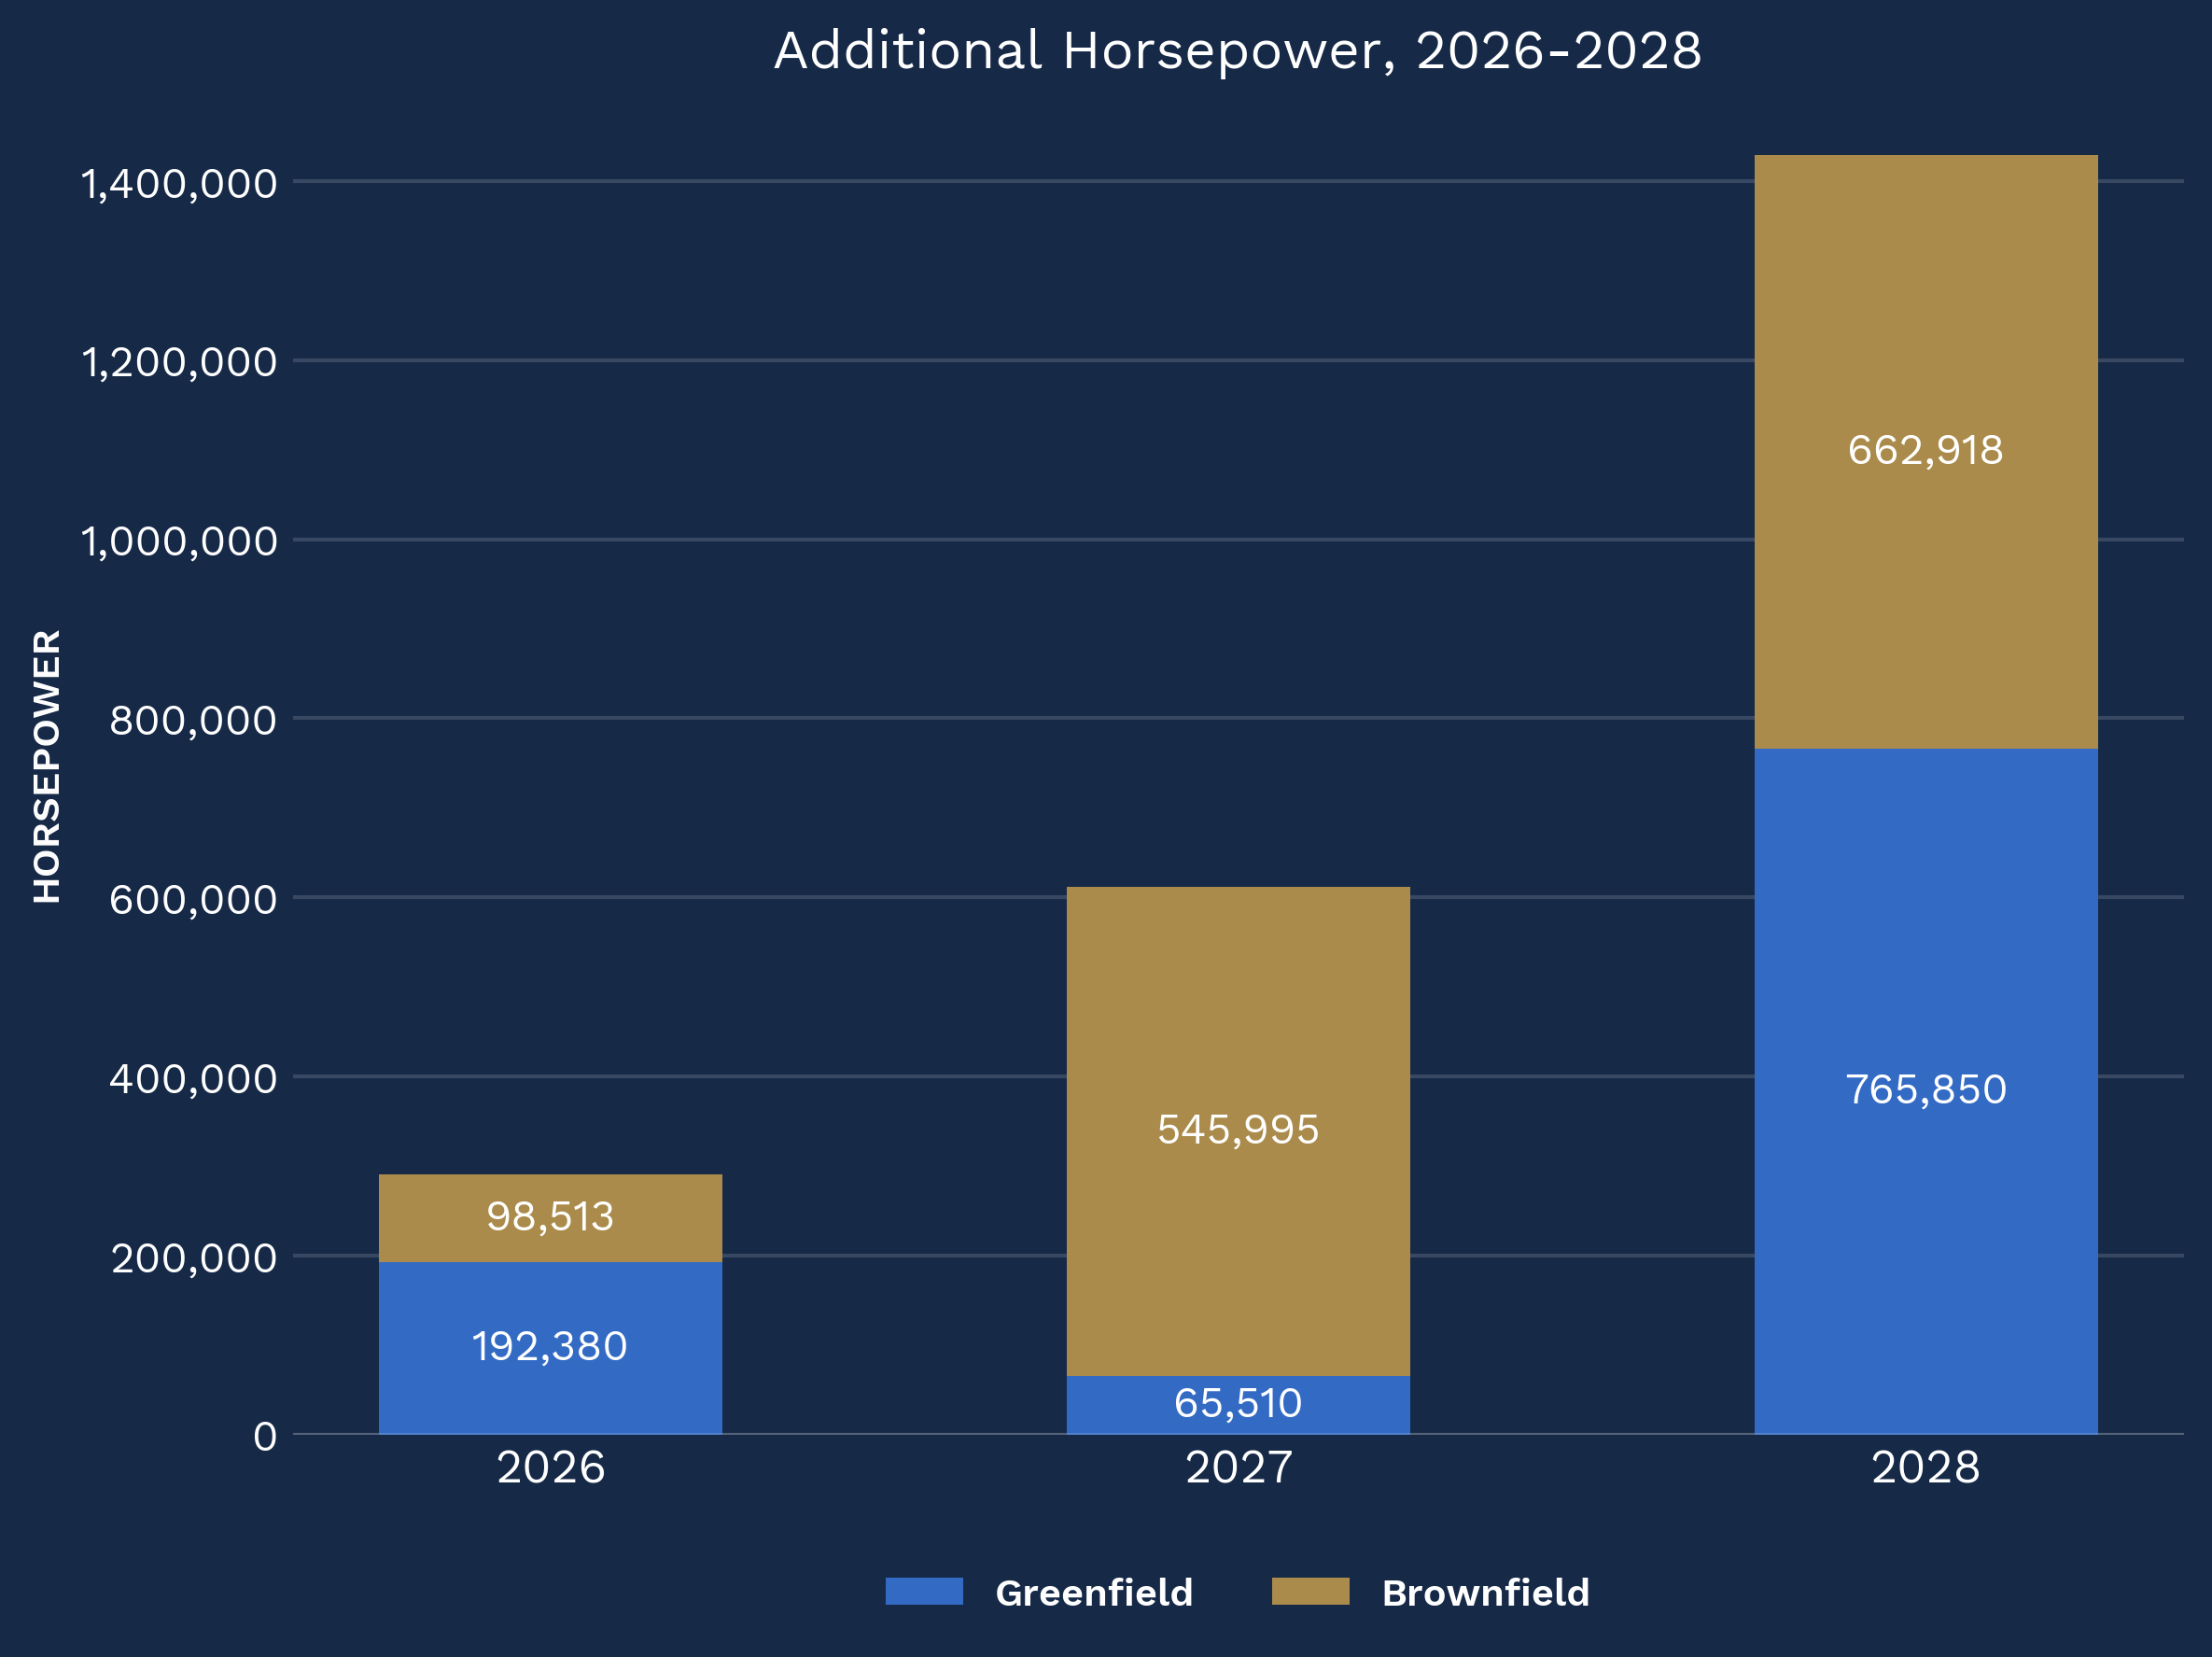
This suggests the second phase of the buildout is becoming more physically intensive, with developers proposing more pipe over longer distances and installing more compression. Average project length reflects this shift. The average mileage-bearing interstate project scheduled for 2028 is roughly 35% longer than one planned for 2026, and 55% longer than one scheduled for 2027. Median project mileage climbs too, from about 18 miles in 2026 and 26 miles in 2027 to 29 miles in 2028.
This increase in both size and scale of construction raises an important question about whether the regulatory and legal challenges surrounding pipeline development will intensify alongside the projects themselves. Because longer pipelines and increased compression generally increase the risk of routing, landowner, environmental, and permitting disputes, developers looking to serve this emerging demand may face more opposition.
The geographic evolution of the project queue provides another view of the growth in development.
As the interactive map below shows, projects entering service in 2026 and 2027 are heavily concentrated around major supply corridors and Gulf Coast infrastructure, particularly projects moving Permian and Haynesville supply toward hubs such as Agua Dulce and Katy and LNG demand along the Texas and Louisiana coasts.
The 2028–2030 map is more geographically dispersed and includes fewer total capacity additions in Texas and Louisiana.
In 2026–2027, several market areas primarily function as destinations or transit hubs for large volumes of newly developed supply. By 2028–2030, some of those same markets begin to move gas onward to other parts of the country.
Northeast Texas illustrates this transition. In 2026 and 2027, projects largely bring gas into the area or connect it with Gulf Coast corridors, resulting in approximately 2.3 Bcf/d of net inbound capacity. In 2028–2030, planned projects take more capacity from Northeast Texas and move gas toward Louisiana and eastern demand markets, resulting in approximately 1.8 Bcf/d of net outbound capacity.
Broadly, the 2026-2027 phase is about building the backbone: evacuating growing supply and connecting it with major transport areas. The next phase increasingly fills in the network. Three regional patterns stand out.
Agua Dulce, Katy, and Southeast Texas often appear relatively balanced when measured on a net inflow-versus-outflow basis. But that net view can understate the scale of development occurring around these hubs.
These markets increasingly function as aggregation and redistribution centers: gas enters from multiple producing regions, is pooled within highly interconnected systems, and is then redirected toward Gulf Coast demand, particularly LNG export facilities. As a result, inflows and outflows can largely offset one another even while the total volume of new pipeline capacity moving through the market is substantial.
Katy illustrates this dynamic. Approximately seven Bcf/d of pipeline capacity associated with the region is expected to be developed in 2026–2027 when inbound and outbound projects are considered together. When including projects slated for 2028–2030, that figure increases to more than 11 Bcf/d in aggregate.
The same dynamic appears around Agua Dulce and parts of Southeast Texas. A near-zero net balance indicates the market is handling large two-way volumes because it sits at the center of an increasingly interconnected pipeline network.
This distinction becomes more important as the Gulf Coast buildout matures. The 2028-2030 phase of development will expand the capacity of the hubs that connect those basins with multiple LNG terminals, industrial loads, and downstream pipeline systems.
As we noted over a year ago in A Pipeline Renaissance on the Eastern Seaboard?, the Southeast shows why LNG is no longer the only major driver of the next infrastructure cycle.
The region shows one of the clearest changes between the two development windows. In 2026–2027, Southeast Supply Enhancement accounts for much of the visible development activity. By 2028–2030, the project queue broadens substantially, with Mississippi Crossing, South System Expansion 4, Kosciusko Junction, MVP Southgate, Hinds-to-Kosci, FGT Phase IX, and other expansions extending development across a much larger portion of the region.
Approximately 7.3 Bcf/d of tracked development in the second phase of the buildout is associated with the Southeast. Of that total, approximately 74% is intra-market. That total can overstate the concentration of development because the Southeast spans numerous states, pipeline systems, and distinct demand centers. As a result, the aggregate capacity figure combines projects serving markets that can be hundreds of miles apart.
This also helps explain why the Southeast development wave is likely to be more infrastructure-intensive. Serving dispersed demand often requires reinforcing multiple segments of the network through looping, compression, and other system modifications rather than constructing a single high-capacity corridor connecting supply with one destination.
The Midcontinent (Midcon) provides another example of demand-driven development, although different from the Southeast.
Projects in the 2028–2030 Midcon queue are entirely intra-market, and the average length of mileage-bearing projects actually declines slightly from 2027 to 2028. Rather than relying on large new pipelines into or out of the region, developers are proposing a collection of shorter, localized expansions, several of which are tied to new or converted gas-fired generation and data center demand.
Appalachia and the Marcellus provide a contrast. Despite remaining one of the country’s largest natural gas-producing regions, it is largely absent from the biggest clusters of new pipeline development in our dataset. Some smaller intrastate projects may be underrepresented, but there is little evidence of a new wave of large-scale interstate takeaway capacity.
The limited project response reinforces a long-standing constraint for the basin. Building new takeaway out of Appalachia remains difficult, even with substantial low-cost supply.
That constraint becomes particularly notable when considering the demand growth in the Southeast, which is generating a meaningful infrastructure response. But much of the supply will be coming from producing regions such as the Haynesville and Permian rather than from Appalachia.
One potential explanation is cost and ease of execution. Building intrastate takeaway in Texas and Louisiana is just easier. Developers could be opting for that path rather than taking on the regulatory and siting challenges in Appalachia.
The next pipeline cycle will depend less on a handful of major LNG-driven corridors and more on sustained, incremental development across multiple regions. The basins that adapt fastest will likely be those where regulatory and siting paths are clearest, not necessarily those with the cheapest supply.
Browse recent blogs about a similar topic.
U.S. gas storage stayed flat as LNG exports surged. Arbo tracks Texas gas storage projects through Railroad Commission permits, not developer claims.

FERC’s July meeting set a mandatory NERC data center reliability standards deadline and cleared Leaf River’s storage expansion.

Two western gas pipeline permitting cases at FERC diverge early: Desert Southwest drew nine pre-scoping comments, Bakken East drew none.